Weekly Narrative Radar · W45 · 30 Oct–6 Nov 2026
Near-trillion commitments meet mega-rounds
Part 1 · Narratives
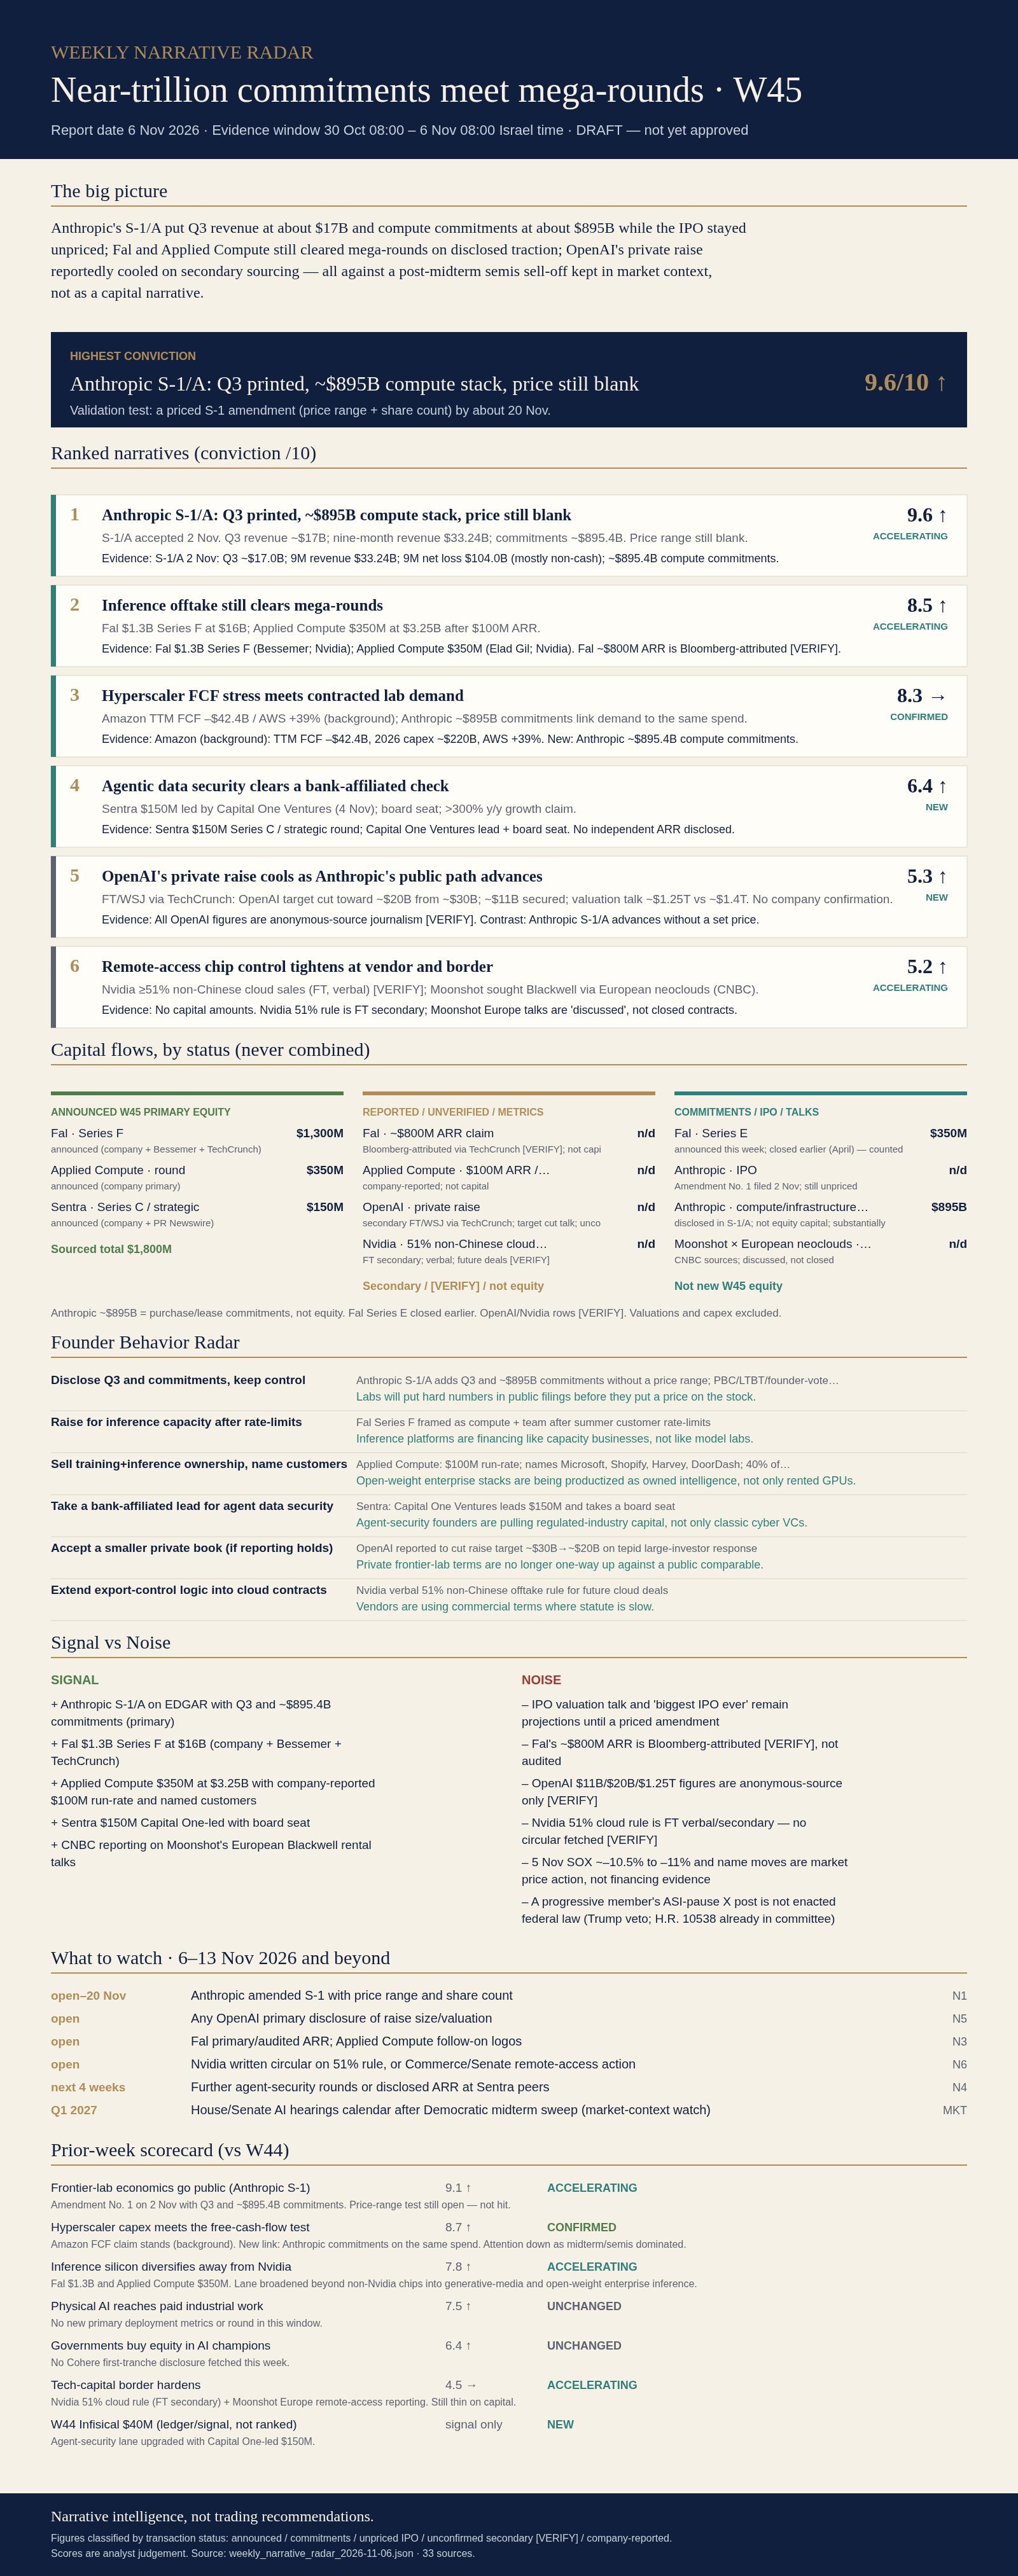
Infographic: PNG (full resolution) · SVG · PDF · dataset JSON · quality gate
DRAFT — not yet approved by the editor. Report date 2026-11-06. Evidence window: Fri 30 Oct 2026 08:00 (W44 cutoff) to Fri 6 Nov 2026 ~08:00, Israel time (Asia/Jerusalem, UTC+2). Friday BLS payrolls (08:30 ET / 15:30 Israel) fall after cutoff and are not covered.. Narrative intelligence, not trading recommendations. Market context, not investment advice.
Near-trillion commitments meet mega-rounds
Thesis. Anthropic's S-1/A put Q3 revenue at about $17B and compute commitments at about $895B while the IPO stayed unpriced; Fal and Applied Compute still cleared mega-rounds on disclosed traction; OpenAI's private raise reportedly cooled on secondary sourcing — all against a post-midterm semis sell-off kept in market context, not as a capital narrative.
S1. TL;DR
- Single most important change: Anthropic's S-1/A (2 Nov) put Q3 revenue at about $17B and compute commitments at about $895.4B while the IPO stayed unpriced [S1A][CNBCANT].
- Three most consequential narratives: Anthropic S-1/A: Q3 printed, ~$895B compute stack, price still blank (9.6/10 ↑); Inference offtake still clears mega-rounds (8.5/10 ↑); Hyperscaler FCF stress meets contracted lab demand (8.3/10 →).
- Highest-conviction positive: Anthropic S-1/A: Q3 printed, ~$895B compute stack, price still blank (9.6/10 ↑).
- Most consequential stress: Hyperscaler FCF stress meets contracted lab demand (8.3/10 →). Hyperscaler FCF stress is confirmed and now tied to filed lab commitments; the post-midterm semis sell-off stays in market context only.
- Where capital concentrates: inference and agent-security platforms. $1,800M in announced W45 primary equity across 3 sourced rounds (Fal $1,300M, Applied Compute $350M, Sentra $150M). Anthropic's ~$895B commitments and Fal's earlier Series E are counted separately.
- Most important question for next week: does Anthropic file a priced S-1 amendment (price range + share count) by about 20 Nov?
S2. Ranked narratives
| Rank | Narrative | Score/10 | Direction | Capital evidence | Conviction |
|---|---|---|---|---|---|
| 1 | Anthropic S-1/A: Q3 printed, ~$895B compute stack, price still blank | 9.6 | ↑ ACCELERATING | S-1/A filed; offering unpriced; ~$895B commitments disclosed | High |
| 2 | Inference offtake still clears mega-rounds | 8.5 | ↑ ACCELERATING | $1.3B Fal Series F; $350M Applied Compute | High |
| 3 | Hyperscaler FCF stress meets contracted lab demand | 8.3 | → CONFIRMED | Filed lab commitments + Amazon FCF (background) | High |
| 4 | Agentic data security clears a bank-affiliated check | 6.4 | ↑ NEW | $150M Sentra, Capital One-led | Medium |
| 5 | OpenAI's private raise cools as Anthropic's public path advances | 5.3 | ↑ NEW | Reported private-raise cut [VERIFY]; no company confirmation | Low |
| 6 | Remote-access chip control tightens at vendor and border | 5.2 | ↑ ACCELERATING | No amounts; vendor policy + remote-access reporting | Low |
| Scores are analyst-rated factors (0–5 each), weighted capital 25 / adoption 25 / founder 20 / corroboration 20 / attention 10, scaled to 10. They are not measured data. Material changes vs W44: N1 9.1→9.6 (adoption 4→5 on filed Q3); inference 7.8→8.5 (Fal+AC mega-rounds); hyperscaler FCF 8.7→8.3 (confirmed, attention down); new Sentra 6.4 and OpenAI-raise 5.3 (secondary); remote-access 4.5→5.2. Midterms/SOX deliberately not scored. | |||||
| ### S3. Deep analysis | |||||
| ### 1. Anthropic S-1/A: Q3 printed, ~$895B compute stack, price still blank: 9.6/10 ↑ (ACCELERATING; prior: W44 N1 · 9.1) | |||||
| Core claim. Amendment No. 1 turns Anthropic from a half-year snapshot into a live IPO process with disclosed Q3 economics and an explicit ~$895B compute-commitment stack, while offer size and price remain unset. | |||||
| Why it matters. Filed Q3 and near-trillion commitments are now the public benchmark for frontier-lab unit economics and for how much of the hyperscaler build-out is already contracted demand. | |||||
| Evidence and capital flows. | |||||
| - Anthropic filed Amendment No. 1 to Form S-1 on EDGAR on 2 Nov 2026; share count and price range remain blank; Nasdaq ticker still ANT [S1A][S1IDX]. | |||||
| - Per the filing and CNBC's write-up: Q3 revenue about $17.0B (CNBC: ~1,127% y/y; QoQ growth slowed to ~47% from ~144% in Q2); nine-month revenue $33.242B; nine-month net loss $104.039B, mostly fair-value changes on convertibles/derivatives [S1A][CNBCANT]. | |||||
| - Aggregate purchase and lease commitments about $895.4B, substantially all compute/infrastructure; about $447.5B expected before end-2030; about $69.8B due in the 12 months after 30 Sep 2026 [S1A][CNBCANT]. | |||||
| - Reuters notes the filing flags partner financing risk: if compute providers lose third-party financing, contracted capacity may be delayed, repriced or not delivered [REUTANT]. | |||||
| Founder and company behavior. The company kept the public-benefit / Long-Term Benefit Trust board-majority design and founder Class F 50.1% vote structure disclosed in the original S-1, while adding hard Q3 and commitment numbers without setting a price [S1A]. | |||||
| Evidence vs hype. Verified: the amendment, Q3/nine-month figures and the $895.4B commitment stack on EDGAR. Unproven: IPO size, valuation and timing. Net-loss headlines are dominated by non-cash fair-value marks. | |||||
| Invalidation. No price-range amendment by about 20 Nov, a postponed offering, or an SEC review that forces a material restatement of Q3 or commitment figures. | |||||
| Monitor next week. Amended S-1 with price range and share count; roadshow timing. | |||||
| Verdict. W44's lead accelerated: amendment landed with Q3 and commitments, but the price-range test is still open. Score rises on adoption (revenue now quarterly-filed, not half-year only). | |||||
| Factors: capital 5, adoption 5, founder 4, corroboration 5, attention 5 (each 0–5). | |||||
| ### 2. Inference offtake still clears mega-rounds: 8.5/10 ↑ (ACCELERATING; prior: W44 N3 · 7.8 (broadened)) | |||||
| Core claim. While hyperscaler cash flow is punished in public markets, specialized inference and enterprise-model platforms still cleared billion- and near-billion-dollar rounds on disclosed revenue traction. | |||||
| Why it matters. Private capital is still paying up for inference platforms with disclosed traction even as public markets punish AI hardware — a public/private split inside the same theme. | |||||
| Evidence and capital flows. | |||||
| - Fal announced Series F of $1.3B at a $16B valuation on 3 Nov, led by Bessemer with Nvidia, Sound Ventures and T. Rowe Price participating; Series E+F combined $1.65B (Sequoia led E) [TCFAL][BVPFAL][FALBLOG]. | |||||
| - TechCrunch, citing Bloomberg: Fal surpassed about $800M in annualized revenue earlier this year — attributed to Bloomberg/'person familiar', not an audited disclosure [VERIFY] [TCFAL]. | |||||
| - Applied Compute (2 Nov, company primary): raised $350M at $3.25B led by Elad Gil with Nvidia among participants; company reports $100M annualized revenue run rate, >1T tokens/day inference, and 1,700+ training runs on its agent cloud, naming customers including Microsoft, Shopify, Harvey and DoorDash [AC]. | |||||
| Founder and company behavior. Fal framed the raise as compute capacity plus team for generative-media inference after summer rate-limits; Applied Compute is selling training+inference ownership of open-weight stacks to named enterprises rather than only renting GPUs [FALBLOG][AC][TCFAL]. | |||||
| Evidence vs hype. Verified: Fal's round size/valuation from company/Bessemer/TechCrunch; Applied Compute's round and $100M run-rate from the company. Unverified: Fal's $800M ARR (Bloomberg-attributed). Thin gross margins across inference peers are widely reported color, not a measured figure here. | |||||
| Invalidation. Next two quarters show Fal or Applied Compute missing disclosed run-rate claims, or no further named enterprise logos. | |||||
| Monitor next week. Fal audited/primary ARR disclosure; Applied Compute follow-on customer metrics. | |||||
| Verdict. W44's non-Nvidia/inference lane broadened into generative-media and open-weight enterprise stacks with larger completed checks. | |||||
| Factors: capital 5, adoption 4, founder 4, corroboration 4, attention 4 (each 0–5). | |||||
| ### 3. Hyperscaler FCF stress meets contracted lab demand: 8.3/10 → (CONFIRMED; prior: W44 N2 · 8.7) | |||||
| Core claim. The free-cash-flow test from W44 stays in force: hyperscaler AI capex can stay deeply cash-flow negative even as cloud growth runs hot, and Anthropic's disclosed ~$895B commitments show how much of that spend is already spoken for by labs. | |||||
| Why it matters. If lab demand is already contracted in the hundreds of billions while hyperscaler free cash flow is negative, the next financing leg (debt, partner credit, IPO proceeds) decides who can keep building. | |||||
| Evidence and capital flows. | |||||
| - Amazon Q3 (29 Oct, background from W44): AWS sales +39.3% to $46.0B; trailing-twelve-month free cash flow an outflow of $42.4B; 2026 cash capex about $220B [AMZN][CNBCAMZN]. | |||||
| - About Amazon / call color (background): AWS backlog cited around $578B; management guided 'meaningfully more' capex in 2027 [AMZNBLOG][CNBCAMZN]. | |||||
| - New in-window link: Anthropic's S-1/A discloses ~$895.4B aggregate compute/infrastructure commitments, of which ~$69.8B is due within 12 months of 30 Sep — contracted offtake sitting on the same hyperscaler balance sheets that printed negative FCF [S1A][CNBCANT]. | |||||
| - Reuters: Anthropic warns some partners depend on third-party financing; if that financing tightens, capacity can slip [REUTANT]. | |||||
| Founder and company behavior. Hyperscaler guides from W44 were not cut this week; the new founder/company move is Anthropic putting the commitment stack into a public filing rather than keeping it private [S1A]. | |||||
| Evidence vs hype. Verified: Amazon filed numbers (background) and Anthropic commitment figures (primary). Interpretation: midweek Amazon price action and the 5 Nov semis session are market noise, not a change in spending plans. 'AI bubble bursting' still overstates held/rising capex guides. | |||||
| Invalidation. Q4 FCF turns clearly positive at Amazon/Alphabet while 2027 capex is cut, or Anthropic's commitment figure is restated sharply lower. | |||||
| Monitor next week. Any hyperscaler commentary on 2027 capex after the midterm/siting debate; Anthropic priced S-1. | |||||
| Verdict. Confirmed, not broken. Score edges down on attention as politics/semis dominated headlines; the structural claim is unchanged and now tied to filed lab commitments. | |||||
| Factors: capital 5, adoption 4, founder 3, corroboration 5, attention 3 (each 0–5). | |||||
| ### 4. Agentic data security clears a bank-affiliated check: 6.4/10 ↑ (NEW; prior: absorbs W44 Infisical signal ($40M)) | |||||
| Core claim. Security for AI-agent access to enterprise data moved from a single growth round (Infisical in W44) to a larger strategic check with a bank-affiliated lead and a board seat. | |||||
| Why it matters. Enterprises deploying agents against sensitive data estates need identity and data-at-rest controls; capital is starting to price that bottleneck. | |||||
| Evidence and capital flows. | |||||
| - Sentra announced a $150M investment led by Capital One Ventures on 4 Nov, with a Capital One representative joining the board; existing backers include Bessemer, Zeev, Standard, Munich Re Ventures and Key1 [SENTRA][SENTRAIO][AXIOSENT]. | |||||
| - Company framing: protect data at rest and control which human and AI identities can reach it; claims >300% year-over-year growth. No independent ARR figure in the release [SENTRA]. | |||||
| - Background: Infisical's $40M round (27 Oct, W44) was the prior week's agent-economy security check [INF]. | |||||
| Founder and company behavior. A regulated-industry corporate venture arm took the lead and a board seat, upgrading lead quality versus a standard growth round [SENTRA][AXIOSENT]. | |||||
| Evidence vs hype. Verified: the round size and Capital One lead from company/PR/Axios. Company-framed: growth % and 'agentic' category branding. One round does not make a category. | |||||
| Invalidation. No further agent-security rounds or material incidents through Q1 2027. | |||||
| Monitor next week. Next agent-security round; any disclosed ARR or named bank/enterprise logos beyond the lead investor. | |||||
| Verdict. Real upgrade in lead quality from W44's Infisical signal; still early on adoption evidence. | |||||
| Factors: capital 4, adoption 2, founder 3, corroboration 4, attention 3 (each 0–5). | |||||
| ### 5. OpenAI's private raise cools as Anthropic's public path advances: 5.3/10 ↑ (NEW; prior: new (secondary)) | |||||
| Core claim. Private frontier-lab fundraising is showing price discovery under stress even as Anthropic pushes a public S-1 process — the capital regime is no longer one-way up. | |||||
| Why it matters. Public vs private capital paths for frontier labs diverged inside one week; that changes relative pricing power for the next raises. | |||||
| Evidence and capital flows. | |||||
| - TechCrunch 31 Oct summarizes FT and WSJ: OpenAI cutting a ~$30B target toward ~$20B after ~$11B of commitments, with desired valuation talked down toward ~$1.25T from ~$1.4T [TCOAI]. | |||||
| - Investing.com rewrite of FT (30 Oct, early-window/background): target cut by about $10B; UAE/MGX expected as a large participant [RTROAI]. | |||||
| - Same-week contrast: Anthropic's S-1/A advances the public path without pricing [S1A][CNBCANT]. | |||||
| Founder and company behavior. If the secondary reporting holds, OpenAI is accepting a smaller book rather than forcing the original ask — while Anthropic chose disclosure over a priced private round this week [TCOAI][S1A]. | |||||
| Evidence vs hype. All primary OpenAI figures remain anonymous-source journalism with no company confirmation fetched. Do not treat $11B/$20B/$1.25T as final. Corroboration is deliberately scored low. | |||||
| Invalidation. OpenAI announces a closed round at or above the original $30B/$1.4T ask, or Anthropic files a priced amendment that clears into a hot book. | |||||
| Monitor next week. Any OpenAI primary disclosure; Anthropic priced S-1/A. | |||||
| Verdict. Directionally important if true, but evidence quality caps the score. Kept as a narrative with loud [VERIFY] flags rather than dropped, because the public/private contrast is the week's second story. | |||||
| Factors: capital 3, adoption 2, founder 3, corroboration 2, attention 4 (each 0–5). | |||||
| ### 6. Remote-access chip control tightens at vendor and border: 5.2/10 ↑ (ACCELERATING; prior: W44 N6 · 4.5) | |||||
| Core claim. Control is moving from physical chip shipment to who may consume advanced GPUs through overseas clouds — vendor policy and Chinese lab behavior both moved this week. | |||||
| Why it matters. Rules on who may consume GPUs remotely decide where inference capacity can be sold and which labs get locked out without a domestic chip path. | |||||
| Evidence and capital flows. | |||||
| - FT via Investing.com (3 Nov): Nvidia verbally tells data-center/cloud partners that at least 51% of services on future deals must go to non-Chinese customers; existing contracts exempt [VERIFY] [NVDAFT]. | |||||
| - CNBC 5 Nov: Moonshot AI sought Nvidia Blackwell capacity via European neoclouds (clusters of 8k+ GPUs discussed); remote-access loophole; RASA bill still stuck in Senate [CNBCMOON]. | |||||
| - Background: Treasury outbound-investment / COINS NPRM (22 Oct) remains the capital-side track [TREAS]. | |||||
| Founder and company behavior. A US chip vendor is using commercial contract terms to extend export-control logic into cloud offtake mix, while a Chinese lab routes around physical shipment limits via European rental [NVDAFT][CNBCMOON]. | |||||
| Evidence vs hype. Verified at T2: CNBC's Moonshot reporting. Secondary only: Nvidia's 51% rule rests on FT anonymous sourcing plus rewrites — no public vendor circular fetched. Moonshot talks are discussed, not announced closed contracts. | |||||
| Invalidation. Nvidia walks back the 51% guidance in writing, or Commerce/Senate closes the remote-access loophole with clear cloud rules within a quarter. | |||||
| Monitor next week. Any Nvidia written circular; Commerce/Senate action on remote access; named European neocloud contracts. | |||||
| Verdict. Policy direction accelerated from W44's border narrative, but capital and adoption evidence remain thin — score stays low. | |||||
| Factors: capital 2, adoption 2, founder 3, corroboration 3, attention 4 (each 0–5). | |||||
| ### S4. Capital Flow Ledger | |||||
| Company / transaction | Amount (US$M) | Type | Status | Source | |
| --- | --- | --- | --- | --- | |
| Fal · Series F | 1,300 | primary equity | announced (company + Bessemer + TechCrunch) | TCFAL | |
| Applied Compute · round | 350 | primary equity | announced (company primary) | AC | |
| Sentra · Series C / strategic | 150 | primary equity | announced (company + PR Newswire) | SENTRA | |
| Fal · Series E (announced alongside F; Sequoia) | 350 | primary equity | announced this week; closed earlier (April) — counted separately, not added to W45 new primary total | FALBLOG | |
| Fal · ~$800M ARR claim | n/d | commercial metric | Bloomberg-attributed via TechCrunch [VERIFY]; not capital | TCFAL | |
| Applied Compute · $100M ARR / run-rate | n/d | commercial metric | company-reported; not capital | AC | |
| Anthropic · IPO (S-1/A) | n/d | IPO process | Amendment No. 1 filed 2 Nov; still unpriced | S1A | |
| Anthropic · compute/infrastructure commitments | 895,400 | commercial purchase/lease commitments | disclosed in S-1/A; not equity capital; substantially all compute | S1A | |
| OpenAI · private raise (reported) | n/d | reported private financing | secondary FT/WSJ via TechCrunch; target cut talk; unconfirmed [VERIFY] | TCOAI | |
| Nvidia · 51% non-Chinese cloud offtake rule | n/d | vendor commercial policy | FT secondary; verbal; future deals [VERIFY] | NVDAFT | |
| Moonshot × European neoclouds · Blackwell rental | n/d | reported capacity talks | CNBC sources; discussed, not closed | CNBCMOON | |
| Totals (comparable, non-overlapping categories only): announced W45 primary equity, sourced (excl. earlier-closed Series E): $1,800M (3 rounds: Fal Series F $1,300M, Applied Compute $350M, Sentra $150M). Aggregator-only primary equity [VERIFY]: $0M. Commercial purchase/lease commitments disclosed (not equity): Anthropic ~$895,400M. Fal Series E $350M announced alongside F but closed earlier — excluded from the W45 new total. OpenAI raise and Nvidia 51% rule have no confirmed amounts. There is no blended total. Valuations and corporate capex excluded. | |||||
| ### S5. Founder Behavior Radar | |||||
| Behavior | Evidence | Strategic interpretation | |||
| --- | --- | --- | |||
| Disclose Q3 and commitments, keep control | Anthropic S-1/A adds Q3 and ~$895B commitments without a price range; PBC/LTBT/founder-vote structure unchanged [S1A] | Labs will put hard numbers in public filings before they put a price on the stock. | |||
| Raise for inference capacity after rate-limits | Fal Series F framed as compute + team after summer customer rate-limits [TCFAL][FALBLOG] | Inference platforms are financing like capacity businesses, not like model labs. | |||
| Sell training+inference ownership, name customers | Applied Compute: $100M run-rate; names Microsoft, Shopify, Harvey, DoorDash; 40% of customers use both training and inference [AC] | Open-weight enterprise stacks are being productized as owned intelligence, not only rented GPUs. | |||
| Take a bank-affiliated lead for agent data security | Sentra: Capital One Ventures leads $150M and takes a board seat [SENTRA] | Agent-security founders are pulling regulated-industry capital, not only classic cyber VCs. | |||
| Accept a smaller private book (if reporting holds) | OpenAI reported to cut raise target ~$30B→~$20B on tepid large-investor response [VERIFY] [TCOAI] | Private frontier-lab terms are no longer one-way up against a public comparable. | |||
| Extend export-control logic into cloud contracts | Nvidia verbal 51% non-Chinese offtake rule for future cloud deals [VERIFY] [NVDAFT] | Vendors are using commercial terms where statute is slow. | |||
| No sourced evidence of pivots, layoffs or shutdowns among this week's companies [gap]. | |||||
| ### S6. Signal vs Noise | |||||
| SIGNAL | |||||
| - Anthropic S-1/A on EDGAR with Q3 and ~$895.4B commitments (primary) | |||||
| - Fal $1.3B Series F at $16B (company + Bessemer + TechCrunch) | |||||
| - Applied Compute $350M at $3.25B with company-reported $100M run-rate and named customers | |||||
| - Sentra $150M Capital One-led with board seat | |||||
| - CNBC reporting on Moonshot's European Blackwell rental talks | |||||
| NOISE | |||||
| - IPO valuation talk and 'biggest IPO ever' remain projections until a priced amendment | |||||
| - Fal's ~$800M ARR is Bloomberg-attributed [VERIFY], not audited | |||||
| - OpenAI $11B/$20B/$1.25T figures are anonymous-source only [VERIFY] | |||||
| - Nvidia 51% cloud rule is FT verbal/secondary — no circular fetched [VERIFY] | |||||
| - 5 Nov SOX ~–10.5% to –11% and name moves are market price action, not financing evidence | |||||
| - A progressive member's ASI-pause X post is not enacted federal law (Trump veto; H.R. 10538 already in committee) | |||||
| ### S7. Prior-week scorecard (vs W44, approved 30 Oct) | |||||
| Previous narrative | Prior assessment | Current assessment | Evidence of change | ||
| --- | --- | --- | --- | ||
| W44 N1 · Frontier-lab economics go public (Anthropic S-1) | 9.1 ↑ · test: amended S-1 with price range before roadshow (~9 Nov week) / by ~20 Nov | 9.6 ↑ ACCELERATING (W45 N1) | Amendment No. 1 on 2 Nov with Q3 and ~$895.4B commitments [S1A]. Price-range test still open — not hit. | ||
| W44 N2 · Hyperscaler capex meets the free-cash-flow test | 8.7 ↑ | 8.3 → CONFIRMED (W45 N2) | Amazon FCF claim stands (background). New link: Anthropic commitments on the same spend [S1A]. Attention down as midterm/semis dominated. | ||
| W44 N3 · Inference silicon diversifies away from Nvidia | 7.8 ↑ | 8.5 ↑ ACCELERATING (broadened into W45 N3) | Fal $1.3B and Applied Compute $350M [TCFAL][AC]. Lane broadened beyond non-Nvidia chips into generative-media and open-weight enterprise inference. | ||
| W44 N4 · Physical AI reaches paid industrial work | 7.5 ↑ · test: fleet/hours/revenue by mid-2027 | UNCHANGED / parked | No new primary deployment metrics or round in this window. | ||
| W44 N5 · Governments buy equity in AI champions | 6.4 ↑ · test: Cohere tranche / other sovereign stakes | UNCHANGED | No Cohere first-tranche disclosure fetched this week. | ||
| W44 N6 · Tech-capital border hardens | 4.5 → | 5.2 ↑ ACCELERATING (W45 N6) | Nvidia 51% cloud rule (FT secondary) + Moonshot Europe remote-access reporting [NVDAFT][CNBCMOON]. Still thin on capital. | ||
| W44 Infisical $40M (ledger/signal, not ranked) | signal only | 6.4 ↑ NEW (W45 N4 Sentra) | Agent-security lane upgraded with Capital One-led $150M [SENTRA]. | ||
| Partially correct: Anthropic amendment arrived with Q3 and commitments, but the price-range test is still open. Surprise: Fal and Applied Compute still cleared mega-rounds while public AI semis sold off. New: OpenAI private-raise cooling (secondary) against Anthropic's public path. Midterms/SOX kept out of scored narratives. Untested predictions are not counted as validated. | |||||
| ### S8. Highest-conviction narrative | |||||
| Anthropic S-1/A: Q3 printed, ~$895B compute stack, price still blank (9.6/10 ↑). It ranks first because capital, adoption, corroboration and attention are all at the top of the scale: Q3 and ~$895B commitments now sit in a public S-1/A on EDGAR, with CNBC and Reuters independent write-ups. Capital and founder behavior align: full disclosure without giving up the PBC/LTBT/founder-vote structure, and without setting a price. Principal uncertainty: the offering is still unpriced. Single most important validation test: a further amended S-1 with a price range and share count by about 20 Nov. | |||||
| ### S9. What to watch next week (6–13 Nov 2026 and beyond) | |||||
| Priority | Dates | Item | Narrative | ||
| --- | --- | --- | --- | ||
| 1 | open–20 Nov | Anthropic amended S-1 with price range and share count | N1 | ||
| 2 | open | Any OpenAI primary disclosure of raise size/valuation | N5 | ||
| 3 | open | Fal primary/audited ARR; Applied Compute follow-on logos | N3 | ||
| 4 | open | Nvidia written circular on 51% rule, or Commerce/Senate remote-access action | N6 | ||
| 5 | next 4 weeks | Further agent-security rounds or disclosed ARR at Sentra peers | N4 | ||
| 6 | Q1 2027 | House/Senate AI hearings calendar after Democratic midterm sweep (market-context watch) | MKT | ||
| ### S10. Market context (separate; no trading signals) | |||||
| - Democratic midterm sweep (House + Senate control per CBS/USA TODAY early counts) put AI regulation and local data-center siting into the political conversation. Rep. Yassamin Ansari (4 Nov) called for a day-1 agenda to pause advanced AI, regulate the industry and ban ASI; H.R. 10538 (Ban Artificial Superintelligence Act) was already filed in late Sep as background [CBS26][USA4][ANSARIX][TOMS][HR10538]. | |||||
| - USA TODAY: 30+ local data-center ballot proposals across 13 states, almost all passed; Cleanview cited that newly elected governors could affect a large share of planned US data-center capacity — framed around power, water and noise as much as 'stop ASI' [USA4][TOMS]. | |||||
| - 5 Nov session: PHLX Semiconductor Index fell about 10.5–11% (Investing.com historical –10.54%; Reuters/NBC ~11% / worst since Mar 2020); NVDA roughly –8% to –9%, AMD roughly –15% in session reporting. Attribution is mixed: Qualcomm/Arm prints plus election/siting/AI-trade fatigue [SOXINV][REUTECH][NBC5][YFCHIP]. Price action only — not financing evidence. | |||||
| - Pre-cutoff labor color: JOLTS openings +333k (3 Nov); ADP +86k private jobs in October (4 Nov); ISM Services PMI 54.5 with Prices 73.0 (4 Nov). Friday BLS payrolls due after cutoff [JOLTS][ADP][ISM][CNBCPAY]. | |||||
| - Interpretation: politics and local siting may slow where capacity gets built; they do not by themselves cancel filed lab commitments or completed inference rounds. Federal ASI-ban bills still face a presidential veto. | |||||
| - Not researched this week [unavailable]: credit spreads and primary financing-cost time series. | |||||
| This section is context only. It contains no buy or sell views, price targets, sizing or market-permission calls, and no OSINT. | |||||
| ### Rejected or set-aside evidence | |||||
| - Democratic midterm sweep / ASI-pause / SOX –10.5% as a scored narrative: Price action and member statements are not capital, adoption or completed financing. Kept in S10 market context and as a watch item. Ansari agenda ≠ enacted law. USA4 | |||||
| - Friday 6 Nov BLS payrolls as narrative evidence: Print lands 08:30 ET / 15:30 Israel — after the ~08:00 Israel cutoff. Preview only in market context. CNBCPAY | |||||
| - Fal Series E $350M as new W45 primary equity: Closed earlier (April); announced alongside F this week. Listed in ledger with status note; excluded from W45 new primary total. FALBLOG | |||||
| - Anthropic $895.4B commitments as 'capital raised': Purchase/lease commitments are contracted spend, not equity or debt proceeds. Ledger row typed as commercial commitments; excluded from equity totals. S1A | |||||
| - Physical AI / Bedrock follow-on: No new primary deployment metrics or round in this window. Prior W44 N4 parked. | |||||
| ### Sources | |||||
| - [AC] Applied Compute, Applied Compute hits $100M run rate and raises $350M (2026-11-02). https://appliedcompute.network/company/100m-run-rate-fundraise | |||||
| - [ADP] CNBC, Private companies added 86,000 jobs in October, ADP says (2026-11-04). https://www.cnbc.com/2026/11/04/private-companies-added-86000-jobs-in-october-slightly-higher-than-expected-adp-says.html | |||||
| - [AMZN] Amazon IR, Amazon.com Announces Third Quarter Results (2026-10-29 (background; W44 window)). https://ir.aboutamazon.com/news-release/news-release-details/2026/Amazon-com-Announces-Third-Quarter-Results/ | |||||
| - [AMZNBLOG] About Amazon, Q3 Earnings: Andy Jassy on AWS' 39% year-over-year growth (2026-10-29 (background; W44 window)). https://www.aboutamazon.com/news/company-news/aws-growth-ai-demand-q3-2026-earnings | |||||
| - [ANSARIX] X / @RepYassAnsari, Day-1 Democratic agenda: pause advanced AI, regulate industry, ban ASI (2026-11-04). https://x.com/RepYassAnsari/status/2118054336077127797 | |||||
| - [AXIOSENT] Axios Pro, Data security startup Sentra raises $150M (2026-11-04). https://www.axios.com/pro/enterprise-software-deals/2026/11/04/sentra-capital-one-cybersecurity | |||||
| - [BVPFAL] Bessemer Venture Partners, Investing in fal: the generative media company (2026-11-03). https://www.bvp.com/news/investing-in-fal-the-generative-media-company | |||||
| - [CBS26] CBS News, 2026 midterm election live updates as Democrats prepare to take Congress (2026-11-04). https://www.cbsnews.com/live-updates/midterm-election-results-2026-democrats-house-senate-trump/ | |||||
| - [CNBCAMZN] CNBC, Amazon (AMZN) Q3 earnings report 2026 (2026-10-29 (background; W44 window)). https://www.cnbc.com/2026/10/29/amazon-amzn-q3-earnings-report-2026.html | |||||
| - [CNBCANT] CNBC, Anthropic reports $17 billion in Q3 revenue, purchase commitments of $895.4 billion in revised S-1 (2026-11-02). https://www.cnbc.com/2026/11/02/anthropic-ant-s-1-quarter-financials.html | |||||
| - [CNBCMOON] CNBC, Chinese AI lab Moonshot turned to Europe for Nvidia Blackwell access amid U.S. China curbs, sources tell CNBC (2026-11-05). https://www.cnbc.com/2026/11/05/moonshot-ai-nvidia-chips-europe-china.html | |||||
| - [CNBCPAY] CNBC, October jobs report preview (payrolls due Fri 6 Nov 08:30 ET) (2026-11-05). https://www.cnbc.com/2026/11/05/october-jobs-report-preview.html | |||||
| - [FALBLOG] fal.ai, The work and the people behind the build (Series E/F) (2026-11). https://fal.ai/blog/series-e-f | |||||
| - [HR10538] GovInfo / U.S. Congress, H.R. 10538 — Ban Artificial Superintelligence Act of 2026 (2026-09-24 (background bill)). https://www.govinfo.gov/app/details/BILLS-119hr10538ih | |||||
| - [INF] PR Newswire, Infisical Raises $40 Million at $600 Million Valuation (2026-10-27 (background; W44)). https://www.prnewswire.com/news-releases/infisical-raises-40-million-at-600-million-valuation-to-secure-the-ai-agent-economy-302920994.html | |||||
| - [ISM] Institute for Supply Management, October 2026 ISM Services PMI Report (2026-11-04). https://www.ismworld.org/supply-management-news-and-reports/reports/ism-pmi-reports/services/october/ | |||||
| - [JOLTS] Axios, New data shows labor market strength in September (JOLTS) (2026-11-03). https://www.axios.com/2026/11/03/jolts-labor-market-ai-jobs | |||||
| - [NBC5] NBC News, Stocks plunge as AI worries crush tech shares (2026-11-05). https://www.nbcnews.com/business/markets/tech-stocks-plunge-ai-midterms-rcna607650 | |||||
| - [NVDAFT] Financial Times via Investing.com, Nvidia tells data center partners to limit China sales (2026-11-03). https://www.investing.com/news/stock-market-news/nvidia-tells-data-center-partners-to-limit-china-sales-ft-4993618 | |||||
| - [REUTANT] Reuters via Investing.com, Anthropic revenue growth slows, compute financing risks mount ahead of IPO (2026-11-02). https://www.investing.com/news/stock-market-news/anthropics-quarterly-loss-shrinks-revenue-jumps-ahead-of-blockbuster-ipo-4992139 | |||||
| - [REUTECH] Reuters via Investing.com, Tech-stock rout accelerates retreat from the AI trade (2026-11-05). https://www.investing.com/news/stock-market-news/techstock-rout-accelerates-retreat-from-the-ai-trade-5005205 | |||||
| - [RTROAI] Reuters/FT via Investing.com, OpenAI slashes funding target by $10 billion amid tech rout, FT reports (2026-10-30 (background / early-window)). https://www.investing.com/news/economy-news/openai-slashes-funding-target-by-10-billion-amid-tech-rout-ft-reports-oct-30-4990653 | |||||
| - [S1A] SEC EDGAR, Anthropic, PBC Amendment No. 1 to Form S-1 (2026-11-02). https://www.sec.gov/Archives/edgar/data/2130357/000162828026068676/anthropicpbc-sx1ax1.htm | |||||
| - [S1IDX] SEC EDGAR, Filing index accession 0001628280-26-068676 (2026-11-02). https://www.sec.gov/Archives/edgar/data/2130357/000162828026068676/0001628280-26-068676-index.htm | |||||
| - [SENTRA] PR Newswire / Sentra, Sentra Raises $150 Million for Agentic Data Security as Enterprise AI Adoption Accelerates (2026-11-04). https://www.prnewswire.com/news-releases/sentra-raises-150-million-for-agentic-data-security-as-enterprise-ai-adoption-accelerates-302928476.html | |||||
| - [SENTRAIO] Sentra, Sentra Raises $150M to Secure Data for the Agentic AI Era (2026-11-04). https://sentra.io/news/sentra-raises-150-million-agentic-data-security | |||||
| - [SOXINV] Investing.com, Philadelphia Semiconductor Index historical data (5 Nov 2026) (2026-11-05). https://ca.investing.com/indices/phlx-semiconductor-historical-data | |||||
| - [TCFAL] TechCrunch, AI inference startup Fal doubles its valuation to $16B as demand surges (2026-11-03). https://techcrunch.com/2026/11/03/ai-inference-startup-fal-doubles-its-valuation-to-16b-as-demand-surges/ | |||||
| - [TCOAI] TechCrunch, OpenAI reportedly lowers funding target for new round (2026-10-31). https://techcrunch.com/2026/10/31/openai-reportedly-lowers-funding-target-for-new-round/ | |||||
| - [TOMS] Tom's Hardware, Congresswoman calls for artificial superintelligence ban after Democrats' seismic midterm sweep (2026-11-05). https://www.tomshardware.com/tech-industry/artificial-intelligence/congresswoman-calls-for-artificial-superintelligence-ban-after-democrats-seismic-midterm-sweep-demands-regulation-of-out-of-control-industry-and-pause-on-advanced-ai | |||||
| - [TREAS] U.S. Department of the Treasury, Treasury Issues Proposed Rule to Implement Comprehensive Outbound Investment National Security Act (2026-10-22 (background)). https://home.treasury.gov/news/press-releases/sb0667/ | |||||
| - [USA4] USA TODAY, Democrats won big. What does that mean for AI policy? (2026-11-04). https://www.usatoday.com/story/tech/2026/11/04/democrats-promise-ai-regulation-in-new-congress/92612851007/ | |||||
| - [YFCHIP] Yahoo Finance, Chip stocks get slaughtered as Wall Street heads for its worst post-midterm day since 1896 (2026-11-05). https://finance.yahoo.com/markets/article/chip-stocks-get-slaughtered-as-wall-street-heads-for-its-worst-post-midterm-day-since-1896-163413900.html |
Quality gate: PASS WITH FLAGS (12/12 checks run, 0 failed). Flags: DRAFT — not approved by the editor. Do not promote to production, RSS or email. Midterm/ASI/SOX material deliberately kept out of scored narratives (price action ≠ capital). See REJECTED and S10. OpenAI raise figures are secondary anonymous-source only [VERIFY]; corroboration scored 2/5. Nvidia 51% rule is FT verbal/secondary; no vendor circular fetched [VERIFY]. Fal ~$800M ARR is Bloomberg-attributed via TechCrunch [VERIFY]. Amazon Q3 figures are background (29 Oct, W44 window); used for continuity only. Anthropic $895.4B is purchase/lease commitments, not equity raised — excluded from equity totals. Fal Series E $350M closed earlier; excluded from W45 new primary equity total. Friday BLS payrolls after cutoff — not covered. Factor ratings are analyst judgement, not measured data. No Canva design made. Credit spreads / financing-cost time series not researched [unavailable].
Part 2 · AI ecosystem signals
Near-trillion commitments meet mega-rounds
Weekly Narrative Radar · AI ecosystem signals · W45 · 30 Oct–6 Nov 2026 DRAFT — not yet approved by the editor.
Thesis. Anthropic's S-1/A put Q3 at about $17B and compute commitments at about $895B while the IPO stayed unpriced; Fal and Applied Compute still cleared mega-rounds; OpenAI's private raise reportedly cooled on secondary sourcing.
1. Anthropic S-1/A: Q3 and ~$895B commitments, still unpriced
What happened. On 2 November Anthropic filed Amendment No. 1 to Form S-1 on EDGAR. Q3 revenue about $17.0B; nine-month revenue $33.24B; nine-month net loss $104.0B (mostly non-cash fair-value marks); aggregate compute/infrastructure commitments about $895.4B, of which about $69.8B is due within 12 months of 30 Sep. Share count and price range remain blank [1][2].
Why it matters. Interpretation: W44's lead claim accelerated: lab economics are now quarterly-filed, not half-year only. The commitment stack also ties to hyperscaler free-cash-flow stress (Narrative N2).
Watch next. A priced amendment (price range + share count) by about 20 Nov.
2. Fal $1.3B Series F; Applied Compute $350M
What happened. On 3 November Fal announced a $1.3B Series F at a $16B valuation led by Bessemer with Nvidia participating; Series E+F combined $1.65B [3][4]. On 2 November Applied Compute raised $350M at $3.25B after a company-reported $100M annualized run rate, naming enterprise customers including Microsoft, Shopify, Harvey and DoorDash [5]. Fal's ~$800M ARR figure is Bloomberg-attributed via TechCrunch [VERIFY].
Why it matters. Interpretation: Private inference capital kept clearing mega-rounds even as public AI semis sold off (market context).
Watch next. Fal primary/audited ARR; Applied Compute follow-on logos.
3. Sentra $150M Capital One-led for agentic data security
What happened. On 4 November Sentra announced a $150M investment led by Capital One Ventures, with a Capital One board seat [6].
Why it matters. Interpretation: Upgrades the W44 Infisical signal: agent-data security is attracting regulated-industry corporate venture capital.
Watch next. Disclosed ARR or further agent-security rounds.
4. Remote-access control: Nvidia 51% rule (FT) and Moonshot Europe talks
What happened. FT (3 Nov, secondary) reported Nvidia verbally telling cloud partners that at least 51% of future-deal services must go to non-Chinese customers [VERIFY] [7]. CNBC (5 Nov) reported Moonshot AI sought Nvidia Blackwell capacity via European neoclouds [8].
Why it matters. Interpretation: Control is moving from physical shipment to who may consume GPUs remotely.
Watch next. Any Nvidia written circular; Commerce/Senate remote-access action.
5. OpenAI private raise reportedly cools (secondary)
What happened. TechCrunch (31 Oct) summarizing FT/WSJ: OpenAI cutting a ~$30B target toward ~$20B after ~$11B of commitments, with valuation talk toward ~$1.25T from ~$1.4T. No company confirmation [VERIFY] [9].
Why it matters. Interpretation: If true, public vs private frontier-lab capital paths diverged in the same week as Anthropic's S-1/A.
Watch next. Any OpenAI primary disclosure.
The pattern
Interpretation: Public lab disclosure and private inference fundraising both moved; post-midterm AI-regulation talk and the 5 Nov semis session are kept as market context, not as financing evidence. Forecast (low confidence): a priced Anthropic amendment arrives before the Thanksgiving window.
Radar
| Signal | Layer | Direction | Confidence |
|---|---|---|---|
| Anthropic S-1/A Q3 + ~$895B commitments | Capital / frontier labs | ↑ disclosure | High |
| Fal $1.3B / Applied Compute $350M | Inference / capital | ↑ private capital | High |
| Sentra $150M Capital One-led | Apps / security | ↑ | Medium-High |
| Nvidia 51% + Moonshot Europe | Geopolitics / supply | ↓ tightening | Medium (FT secondary) |
| OpenAI raise cut (reported) | Capital / frontier labs | ↓ private terms | Low (secondary only) |
Market context, not investment advice. Facts carry sources; interpretation and forecasts are labelled. Corrections are timestamped below.
Corrections: none.
Signal sources
- SEC EDGAR: Anthropic, PBC Amendment No. 1 to Form S-1 (2026-11-02)
- CNBC: Anthropic reports $17 billion in Q3 revenue, purchase commitments of $895.4 billion in revised S-1 (2026-11-02)
- TechCrunch: AI inference startup Fal doubles its valuation to $16B as demand surges (2026-11-03)
- Bessemer Venture Partners: Investing in fal: the generative media company (2026-11-03)
- Applied Compute: Applied Compute hits $100M run rate and raises $350M (2026-11-02)
- PR Newswire / Sentra: Sentra Raises $150 Million for Agentic Data Security (2026-11-04)
- Financial Times via Investing.com: Nvidia tells data center partners to limit China sales (2026-11-03)
- CNBC: Chinese AI lab Moonshot turned to Europe for Nvidia Blackwell access (2026-11-05)
- TechCrunch: OpenAI reportedly lowers funding target for new round (2026-10-31)
Signals claim-to-source ledger (JSON)
The Friday email
The ranked narratives, the capital-flow ledger and the AI signals, once a week.
We only use your email to send this newsletter. Unsubscribe anytime.