Weekly Narrative Radar · W44 · 23–30 Oct 2026
The bill for AI arrives in public
What I'd change my mind on
- Anthropic's S-1 (9.1/10). I'd change my mind if there's no amended S-1 with a price range by about 20 Nov, or the SEC forces a restatement of the H1 numbers.
- Hyperscaler capex vs free cash flow (8.7/10). I'd change my mind if Alphabet and Amazon show free cash flow recovering in Q4, or the market rewards the next capex raise regardless.
- Inference silicon off Nvidia (7.8/10). I'd change my mind if non-Nvidia inference clouds can't land a second named large customer within two quarters.
Part 1 · Narratives
Infographic: PNG (full resolution) · SVG · PDF · dataset JSON · quality gate
Approved by the editor, 30 Oct 2026. Report date 2026-10-30. Evidence window: Fri 23 Oct 2026 10:30 (W43 cutoff) to Fri 30 Oct 2026 08:00, Israel time (Asia/Jerusalem; clocks moved from UTC+3 to UTC+2 on 25 Oct). Narrative intelligence, not trading recommendations. Market context, not investment advice.
The bill for AI arrives in public
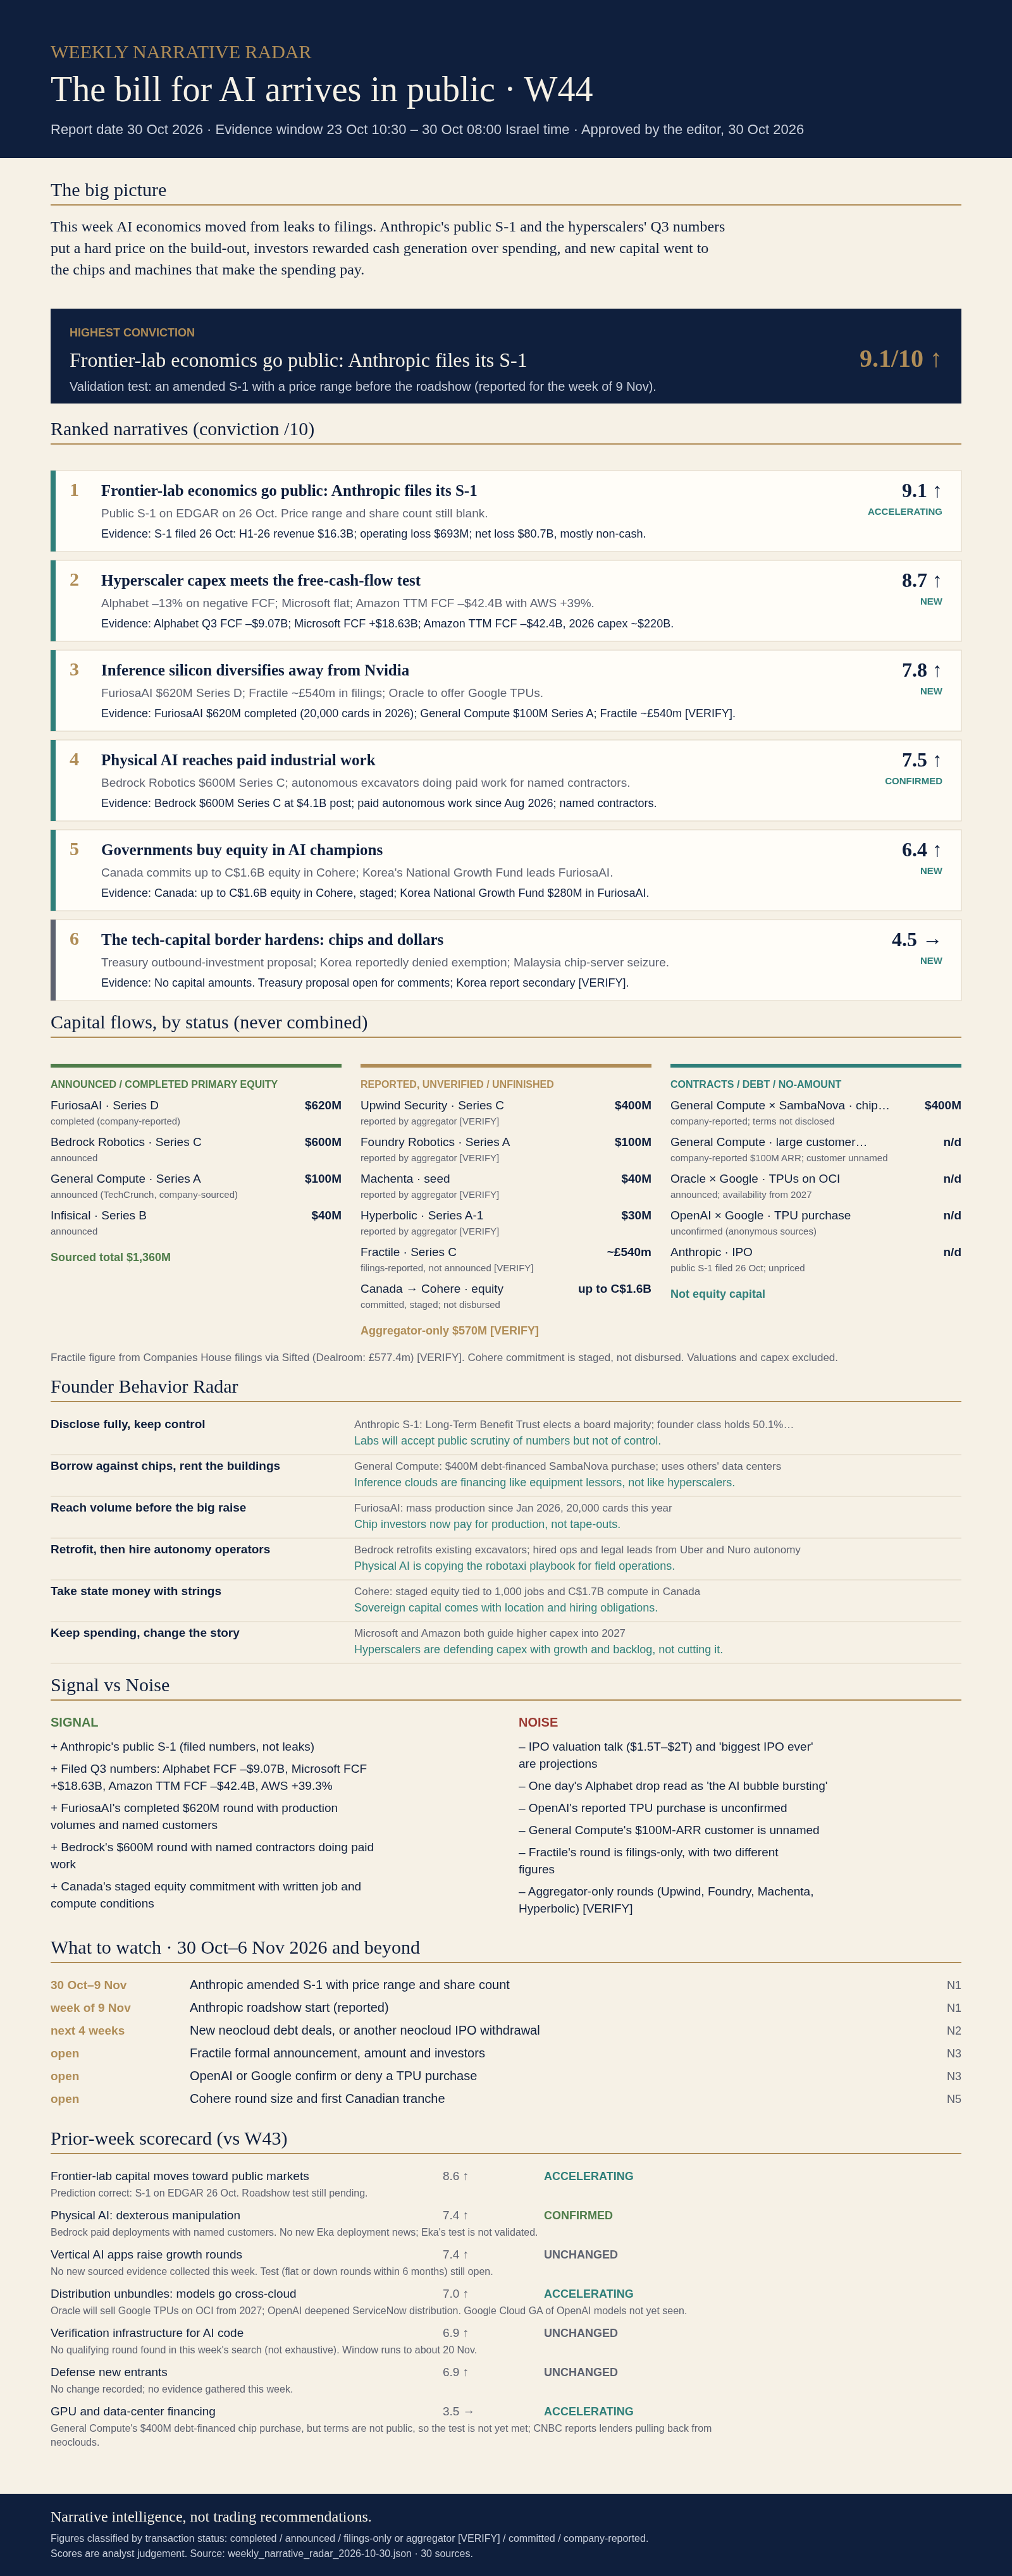
Thesis. This week AI economics moved from leaks to filings. Anthropic's public S-1 and the hyperscalers' Q3 numbers put a hard price on the build-out, investors rewarded cash generation over spending, and new capital went to the chips and machines that make the spending pay.
S1. TL;DR
- Single most important change: frontier-lab and hyperscaler economics are now filed numbers, not leaks. Anthropic's S-1 went public on 26 Oct, and Alphabet's negative free cash flow cost it 13% in a day [S1][CNBC2].
- Three most consequential narratives: Frontier-lab economics go public: Anthropic files its S-1 (9.1/10 ↑); Hyperscaler capex meets the free-cash-flow test (8.7/10 ↑); Inference silicon diversifies away from Nvidia (7.8/10 ↑).
- Highest-conviction positive: Frontier-lab economics go public: Anthropic files its S-1 (9.1/10 ↑).
- Most consequential negative: Hyperscaler capex meets the free-cash-flow test (8.7/10). Free cash flow at Alphabet and Amazon turned negative while capex plans keep rising, and neocloud lenders are pulling back.
- Where capital concentrates: inference chips and physical AI. $1,360M in announced or completed primary equity across 4 sourced rounds, of which FuriosaAI ($620M) and Bedrock ($600M) are 90%. Fractile (~£540m, filings only) and Canada's Cohere commitment (up to C$1.6B) are counted separately.
- Most important question for next week: does Anthropic's amended S-1 set a price range before the roadshow reported for the week of 9 Nov?
S2. Ranked narratives
| Rank | Narrative | Score/10 | Direction | Capital evidence | Conviction |
|---|---|---|---|---|---|
| 1 | Frontier-lab economics go public: Anthropic files its S-1 | 9.1 | ↑ ACCELERATING | S-1 filed; offering unpriced | High |
| 2 | Hyperscaler capex meets the free-cash-flow test | 8.7 | ↑ NEW | Filed Q3 capex and FCF | High |
| 3 | Inference silicon diversifies away from Nvidia | 7.8 | ↑ NEW | $620M completed; $100M; ~£540m filings [VERIFY] | Medium |
| 4 | Physical AI reaches paid industrial work | 7.5 | ↑ CONFIRMED | $600M Series C, announced | Medium |
| 5 | Governments buy equity in AI champions | 6.4 | ↑ NEW | Up to C$1.6B, staged commitment | Medium |
| 6 | The tech-capital border hardens: chips and dollars | 4.5 | → NEW | No amounts | Low |
| Scores are analyst-rated factors (0–5 each), weighted capital 25 / adoption 25 / founder 20 / corroboration 20 / attention 10, scaled to 10. They are not measured data. Material changes vs W43: N1 8.6 to 9.1 (adoption 3 to 4, because revenue is now filed rather than leaked); physical AI 7.4 to 7.5 (adoption 2 to 3 on named paying customers, corroboration 5 to 4 because two rounds are aggregator-only). | |||||
| ### S3. Deep analysis | |||||
| ### 1. Frontier-lab economics go public: Anthropic files its S-1: 9.1/10 ↑ (ACCELERATING; prior: W43 N1 · 8.6) | |||||
| Core claim. Anthropic's public S-1 turns frontier-lab economics into a public benchmark, with the offering itself still unpriced. | |||||
| Why it matters. Its revenue, loss and compute numbers are now the reference point for valuing every frontier lab, private or public. | |||||
| Evidence and capital flows. | |||||
| - Anthropic's public S-1 went up on EDGAR on 26 Oct, ticker ANT, with the share count and price range left blank [S1][ANT]. | |||||
| - TechCrunch, citing the filing: H1 2026 revenue $16.3B (vs $1.2B a year earlier), operating loss $693M, net loss $80.7B driven mostly by non-cash convertible-note fair-value changes [TC1]. | |||||
| - AP: the offering could be the largest IPO ever, with a debut expected next month; that is a projection, not a set size [AP1]. | |||||
| - Yahoo Finance (29 Oct): no price range or share count yet; terms are expected in an amended S-1 before the roadshow [YF2]. | |||||
| Founder and company behavior. The company chose full public disclosure while locking control in place: a public-benefit structure whose Long-Term Benefit Trust elects a board majority, and a founder share class with 50.1% of votes, as reported from the filing [TC1]. | |||||
| Evidence vs hype. Verified: the filing and its H1 numbers. Unproven: the size of the offering, the valuation (the $1.5T–$2T talk from W43 sources is not guidance) and the timing. | |||||
| Invalidation. No amended S-1 with a price range by about 20 Nov, a postponed offering, or an SEC review that forces a material restatement of the H1 numbers. | |||||
| Monitor next week. Amended S-1 with price range and share count; roadshow reported for the week of 9 Nov. | |||||
| Verdict. W43's test passed: the S-1 is public, eleven days before the 6 Nov deadline. Score rises on adoption (revenue now filed, not leaked). | |||||
| Factors: capital 5, adoption 4, founder 4, corroboration 5, attention 5 (each 0–5). | |||||
| ### 2. Hyperscaler capex meets the free-cash-flow test: 8.7/10 ↑ (NEW; prior: new) | |||||
| Core claim. Investors started punishing AI capex that pushes free cash flow negative and rewarding capex backed by visible cloud growth. | |||||
| Why it matters. If financing the build-out from free cash flow stops being possible, the next leg moves to debt and outside capital, which changes who can keep spending. | |||||
| Evidence and capital flows. | |||||
| - Alphabet Q3: free cash flow –$9.07B vs about –$2.7B expected; full-year capex guide held at $195–205B; shares fell 13% on 29 Oct, the worst day since its 2004 listing [CNBC1][CNBC2]. | |||||
| - Microsoft Q3: capex and finance leases $45.2B, below estimates; free cash flow $18.63B, down 27% but positive; Azure +48%; full-year capex forecast cut to $170B from $175B; shares roughly flat [CNBC2][CNBC3]. | |||||
| - Microsoft's CFO said third-party GPU providers' delays push some capacity into H1 2027, and expects capex to accelerate in H1 2027 [CNBC3]. | |||||
| - Amazon Q3 (29 Oct): AWS sales +39.3% to $46.0B; trailing-twelve-month free cash flow an outflow of $42.4B, driven by a $94.8B rise in property and equipment purchases; 2026 cash capex still about $220B [AMZN]. On the call, management cited a $578B AWS backlog and 'meaningfully more' capex in 2027 [AMZT]. | |||||
| - Meta (prior week, background): full-year capex guide $135–145B with negative free cash flow in Q3 [CNBC3][META]. | |||||
| Founder and company behavior. The big spenders are not cutting: Alphabet flagged higher 2027 spending, Microsoft expects capex to accelerate in H1 2027, and Amazon plans 'meaningfully more' in 2027 [CNBC3][AMZT]. What changed is the market's response, not the plans. | |||||
| Evidence vs hype. Verified: the filed quarterly numbers. Interpretation: one day's price reaction is not a regime, and 'AI bubble bursting' is contradicted by rising capex plans and 39–48% cloud growth. | |||||
| Invalidation. Free cash flow recovers in Q4 at Alphabet and Amazon, or the market again rewards the next capex raise regardless of cash flow. | |||||
| Monitor next week. Neocloud debt deals and IPO withdrawals; analyst revisions to 2027 capex. | |||||
| Verdict. A new, well-evidenced narrative. It is about what investors reward, not a change in spending. | |||||
| Factors: capital 5, adoption 4, founder 3, corroboration 5, attention 5 (each 0–5). | |||||
| ### 3. Inference silicon diversifies away from Nvidia: 7.8/10 ↑ (NEW; prior: absorbs W43 N6 (7.0) and N7 (3.5)) | |||||
| Core claim. Capital and capacity deals are moving to non-Nvidia inference chips, as GPU supply delays cap growth at the largest buyers. | |||||
| Why it matters. If inference moves to cheaper non-Nvidia silicon, the cost of serving models falls and the build-out depends less on a single supplier. | |||||
| Evidence and capital flows. | |||||
| - FuriosaAI completed a $620M Series D at about $2.9B post-money, including $280M from South Korea's National Growth Fund; it expects to produce 20,000 RNGD cards in 2026 and over 40,000 in 2027, and names Samsung SDS, LG and Upstage as users [FUR][FURBW]. | |||||
| - Fractile (London, SRAM-based inference chips) raised about £540m in a Series C according to Companies House filings reported by Sifted; Dealroom puts it at £577.4m from the same filings. The company has not announced it [FRS][FRD]. | |||||
| - General Compute raised a $100M Series A at $800M post-money after a $400M SambaNova chip purchase described as the first debt financing of inference chips, and a customer deal worth $100M in annual recurring revenue; the customer is not named [GC]. | |||||
| - Oracle will offer Google TPUs on Oracle Cloud Infrastructure from 2027, the first hyperscale cloud outside Google to do so [ORCL]. The Information reported OpenAI may buy Google TPUs; neither company has confirmed it [TT2]. | |||||
| Founder and company behavior. Inference-cloud founders are buying non-Nvidia chips with borrowed money and renting existing data-center space instead of building it [GC]. Chip startups are reaching volume production before the big raise [FUR]. | |||||
| Evidence vs hype. Verified: FuriosaAI's completed round and production numbers, Oracle's TPU plan, General Compute's round. Unverified: Fractile's amount (filings only, two figures), the OpenAI TPU purchase, and General Compute's unnamed customer. | |||||
| Invalidation. Non-Nvidia inference clouds fail to land a second named large customer within two quarters, or FuriosaAI misses its 2026 production target. | |||||
| Monitor next week. Fractile's formal announcement; confirmation or denial of the OpenAI TPU purchase. | |||||
| Verdict. Real money and real production volumes, but adoption is still early and partly unnamed. | |||||
| Factors: capital 5, adoption 3, founder 4, corroboration 4, attention 3 (each 0–5). | |||||
| ### 4. Physical AI reaches paid industrial work: 7.5/10 ↑ (CONFIRMED; prior: W43 N3 · 7.4 (broadened)) | |||||
| Core claim. Venture money is following autonomy that already does paid work on real sites, starting with construction equipment. | |||||
| Why it matters. Paid autonomous work on job sites is the first step from robotics demos to an operating business in a labor-short industry. | |||||
| Evidence and capital flows. | |||||
| - Bedrock Robotics announced a $600M Series C at a $4.1B post-money valuation, co-led by CapitalG and Emergence, bringing total funding to nearly $1B [BED]. | |||||
| - The company says its excavators have done paid, fully autonomous work on live commercial sites since mid-August 2026 and names contractors including Haydon, Zachry and Champion Site Prep [BED][BEDTC]. | |||||
| - Machenta (London) raised a $40M seed for a robot foundation model (aggregator only) [VERIFY] [RT]. Foundry Robotics raised $100M for autonomous manufacturing (aggregator only) [VERIFY] [TS3]. | |||||
| Founder and company behavior. Bedrock is retrofitting existing machines rather than building new ones, and hired operations and legal leaders from Uber's and Nuro's autonomy programs to scale field deployments [BED]. | |||||
| Evidence vs hype. Verified: the round and the named customers. Company-reported only: 'paid work' and customer counts; no fleet size, operating hours or revenue are disclosed. | |||||
| Invalidation. No disclosed fleet size, operating hours or revenue by mid-2027, or customers fail to expand beyond first sites. | |||||
| Monitor next week. Bedrock customer additions and any operating metrics; Eka (W43) deployment news. | |||||
| Verdict. Adoption evidence improved since W43 (named paying customers vs lab metrics), so the score edges up despite thinner corroboration. | |||||
| Factors: capital 4, adoption 3, founder 4, corroboration 4, attention 4 (each 0–5). | |||||
| ### 5. Governments buy equity in AI champions: 6.4/10 ↑ (NEW; prior: new) | |||||
| Core claim. States are moving from grants to equity stakes in domestic AI companies, with jobs and compute commitments attached. | |||||
| Why it matters. State equity changes who competes in AI: champions can outspend on compute without matching private valuations. | |||||
| Evidence and capital flows. | |||||
| - Canada committed to an equity investment of up to about C$1.6B in Cohere, made in stages, alongside private investors including NVIDIA, Bell and Schwarz Group; Cohere commits to at least 1,000 Canadian technical jobs and at least C$1.7B of compute in Canada by 2030 [CAN]. | |||||
| - South Korea's National Growth Fund put $280M into FuriosaAI's Series D, the largest single investor in the round [FURBW]. | |||||
| Founder and company behavior. Cohere accepted conditions (keeping its Canadian incorporation and headquarters, staged funding tied to reported progress) in exchange for state capital [CAN]. | |||||
| Evidence vs hype. Verified: the commitments as announced by governments and the company. Unproven: how much is disbursed, and the private investors' amounts, which are not disclosed. | |||||
| Invalidation. The Cohere tranches stall or are cut, or no other government takes an equity stake in an AI company within six months. | |||||
| Monitor next week. Cohere round size and first tranche; other sovereign AI equity deals. | |||||
| Verdict. A clear new pattern with primary sources, but these are commitments, not cash yet. | |||||
| Factors: capital 4, adoption 2, founder 3, corroboration 4, attention 3 (each 0–5). | |||||
| ### 6. The tech-capital border hardens: chips and dollars: 4.5/10 → (NEW; prior: W43 AI-signals S4 (Taiwan)) | |||||
| Core claim. Washington is extending control from which chips reach China to which capital flows and which allies get easier licensing. | |||||
| Why it matters. Rules on capital, not just chips, decide where AI supply chains get financed and built. | |||||
| Evidence and capital flows. | |||||
| - Treasury's proposed outbound-investment rules would cover AI, chips, quantum and biotech, with comments taken before final rules [TR]. | |||||
| - The US reportedly declined South Korea's bid for an export-control licence exemption, per Politico and diplomatic sources as reported by IBTimes KR [VERIFY] [KR]. | |||||
| - Malaysian customs seized servers with advanced AI chips suspected of export-control violations (28 Oct) [AP2]. | |||||
| Founder and company behavior. Equipment makers are shifting manufacturing to serve restricted markets from allied countries (reported for ACM Research in Korea) [KR]. | |||||
| Evidence vs hype. Verified: the Treasury proposal and the Malaysian seizure. Secondary only: the Korea decision. Background: a 14 Oct report on a draft 'investment-for-licence' rule has no published text. | |||||
| Invalidation. Treasury narrows the rules sharply after comments, or Korea is added to the exemption list within months. | |||||
| Monitor next week. Treasury comment period; official Commerce statement on Korea. | |||||
| Verdict. Policy direction is clear, but there is no capital or adoption evidence, so it stays low and flat. | |||||
| Factors: capital 1, adoption 2, founder 3, corroboration 3, attention 3 (each 0–5). | |||||
| ### S4. Capital Flow Ledger | |||||
| Company / transaction | Amount (US$M) | Type | Status | Source | |
| --- | --- | --- | --- | --- | |
| FuriosaAI · Series D | 620 | primary equity | completed (company-reported) | FUR | |
| Bedrock Robotics · Series C | 600 | primary equity | announced | BED | |
| General Compute · Series A | 100 | primary equity | announced (TechCrunch, company-sourced) | GC | |
| Infisical · Series B | 40 | primary equity | announced | INF | |
| Fractile · Series C (~£540m; ~$721m per Sifted) | n/d | primary equity | filings-reported, not announced [VERIFY] | FRS | |
| Upwind Security · Series C | 400 | primary equity | reported by aggregator [VERIFY] | TS3 | |
| Foundry Robotics · Series A | 100 | primary equity | reported by aggregator [VERIFY] | TS3 | |
| Machenta · seed | 40 | primary equity | reported by aggregator [VERIFY] | RT | |
| Hyperbolic · Series A-1 | 30 | primary equity | reported by aggregator [VERIFY] | TS1 | |
| Canada → Cohere · equity (up to C$1.6B) | n/d | government equity commitment | committed, staged; not disbursed | CAN | |
| General Compute × SambaNova · chip purchase | 400 | debt-financed equipment purchase | company-reported; terms not disclosed | GC | |
| General Compute · large customer deal | n/d | commercial contract | company-reported $100M ARR; customer unnamed | GC | |
| Oracle × Google · TPUs on OCI | n/d | capacity partnership | announced; availability from 2027 | ORCL | |
| OpenAI × Google · TPU purchase | n/d | reported deal | unconfirmed (anonymous sources) | TT2 | |
| Anthropic · IPO | n/d | IPO process | public S-1 filed 26 Oct; unpriced | S1 | |
| Totals (comparable, non-overlapping categories only): announced or completed primary equity, sourced: $1,360M (4 rounds). Aggregator-only primary equity [VERIFY]: $570M (4 rounds). Filings-only primary equity [VERIFY]: Fractile ~£540m (Sifted) or £577.4m (Dealroom), not converted or added. Government equity commitment: up to C$1.6B (Cohere), staged and not disbursed. Debt-financed equipment purchase: $400M (General Compute × SambaNova). There is no blended total. Valuations, corporate capex and no-amount partnerships are excluded. | |||||
| ### S5. Founder Behavior Radar | |||||
| Behavior | Evidence | Strategic interpretation | |||
| --- | --- | --- | |||
| Disclose fully, keep control | Anthropic S-1: Long-Term Benefit Trust elects a board majority; founder class holds 50.1% of votes [TC1] | Labs will accept public scrutiny of numbers but not of control. | |||
| Borrow against chips, rent the buildings | General Compute: $400M debt-financed SambaNova purchase; uses others' data centers [GC] | Inference clouds are financing like equipment lessors, not like hyperscalers. | |||
| Reach volume before the big raise | FuriosaAI: mass production since Jan 2026, 20,000 cards this year [FUR] | Chip investors now pay for production, not tape-outs. | |||
| Retrofit, then hire autonomy operators | Bedrock retrofits existing excavators; hired ops and legal leads from Uber and Nuro autonomy [BED] | Physical AI is copying the robotaxi playbook for field operations. | |||
| Take state money with strings | Cohere: staged equity tied to 1,000 jobs and C$1.7B compute in Canada [CAN] | Sovereign capital comes with location and hiring obligations. | |||
| Keep spending, change the story | Microsoft and Amazon both guide higher capex into 2027 [CNBC3][AMZT] | Hyperscalers are defending capex with growth and backlog, not cutting it. | |||
| No sourced evidence of pivots, layoffs or shutdowns among this week's companies [gap]. | |||||
| ### S6. Signal vs Noise | |||||
| SIGNAL | |||||
| - Anthropic's public S-1 (filed numbers, not leaks) | |||||
| - Filed Q3 numbers: Alphabet FCF –$9.07B, Microsoft FCF +$18.63B, Amazon TTM FCF –$42.4B, AWS +39.3% | |||||
| - FuriosaAI's completed $620M round with production volumes and named customers | |||||
| - Bedrock's $600M round with named contractors doing paid work | |||||
| - Canada's staged equity commitment with written job and compute conditions | |||||
| NOISE | |||||
| - IPO valuation talk ($1.5T–$2T) and 'biggest IPO ever' are projections | |||||
| - One day's Alphabet drop read as 'the AI bubble bursting' | |||||
| - OpenAI's reported TPU purchase is unconfirmed | |||||
| - General Compute's $100M-ARR customer is unnamed | |||||
| - Fractile's round is filings-only, with two different figures | |||||
| - Aggregator-only rounds (Upwind, Foundry, Machenta, Hyperbolic) [VERIFY] | |||||
| ### S7. Prior-week scorecard (vs W43, approved 25 Oct) | |||||
| Previous narrative | Prior assessment | Current assessment | Evidence of change | ||
| --- | --- | --- | --- | ||
| W43 N1 · Frontier-lab capital moves toward public markets | 8.6 ↑ · test: public S-1 by 6 Nov | 9.1 ↑ ACCELERATING (W44 N1) | Prediction correct: S-1 on EDGAR 26 Oct [S1]. Roadshow test still pending. | ||
| W43 N3 · Physical AI: dexterous manipulation | 7.4 ↑ · test: production deployment by Q1 2027 | 7.5 ↑ CONFIRMED (broadened into W44 N4) | Bedrock paid deployments with named customers [BED]. No new Eka deployment news; Eka's test is not validated. | ||
| W43 N5 · Vertical AI apps raise growth rounds | 7.4 ↑ | UNCHANGED (not re-scored) | No new sourced evidence collected this week. Test (flat or down rounds within 6 months) still open. | ||
| W43 N6 · Distribution unbundles: models go cross-cloud | 7.0 ↑ · test: Google Cloud GA by 31 Dec | ACCELERATING (folded into W44 N3) | Oracle will sell Google TPUs on OCI from 2027 [ORCL]; OpenAI deepened ServiceNow distribution [OAISN]. Google Cloud GA of OpenAI models not yet seen. | ||
| W43 N2 · Verification infrastructure for AI code | 6.9 ↑ · test: another priced round in 4 weeks | UNCHANGED | No qualifying round found in this week's search (not exhaustive). Window runs to about 20 Nov. | ||
| W43 N4 · Defense new entrants | 6.9 ↑ | UNCHANGED (not re-researched) | No change recorded; no evidence gathered this week. | ||
| W43 N7 · GPU and data-center financing | 3.5 → · test: priced GPU-backed debt deal in 4 weeks | ACCELERATING, with a contradiction (folded into W44 N3) | General Compute's $400M debt-financed chip purchase [GC], but terms are not public, so the test is not yet met; CNBC reports lenders pulling back from neoclouds [CNBC3]. | ||
| Correct prediction: the Anthropic S-1 test. Surprise: the market punished Alphabet's free cash flow more than any capex number. New contradiction: chip-backed debt is appearing (General Compute) just as lenders retreat from neoclouds. Untested predictions are not counted as validated. | |||||
| ### S8. Highest-conviction narrative | |||||
| Frontier-lab economics go public: Anthropic files its S-1 (9.1/10 ↑). It ranks first because it has the top marks on capital (5/5), corroboration (5/5) and attention (5/5): the numbers now sit in a public SEC filing and are reported independently by TechCrunch, AP and Yahoo Finance. Capital and founder behavior align: the company chose full disclosure while locking in governance control. Principal uncertainty: the offering is unpriced, so size, valuation and timing are unknown. Single most important validation test: an amended S-1 with a price range and share count before the roadshow reported for the week of 9 Nov. | |||||
| ### S9. What to watch next week (30 Oct–6 Nov 2026 and beyond) | |||||
| Priority | Dates | Item | Narrative | ||
| --- | --- | --- | --- | ||
| 1 | 30 Oct–9 Nov | Anthropic amended S-1 with price range and share count | N1 | ||
| 2 | week of 9 Nov | Anthropic roadshow start (reported) | N1 | ||
| 3 | next 4 weeks | New neocloud debt deals, or another neocloud IPO withdrawal | N2 | ||
| 4 | open | Fractile formal announcement, amount and investors | N3 | ||
| 5 | open | OpenAI or Google confirm or deny a TPU purchase | N3 | ||
| 6 | open | Cohere round size and first Canadian tranche | N5 | ||
| ### S10. Market context (separate; no trading signals) | |||||
| - The Fed held at 3.75–4% on 28 Oct by 10–2; Cook and Hammack dissented in favour of a 25bp hike. The statement called capital investment 'robust' and inflation 'elevated' [FED1]. | |||||
| - Neoclouds' cost of capital is rising and lenders are pulling back, per CNBC; Australia's Firmus withdrew its IPO this month, and Gartner predicts 80% of neoclouds will be absorbed or close by 2030 [CNBC3]. | |||||
| - Public markets separated companies by free cash flow: Alphabet fell 13% (about $500B of value) while Microsoft was roughly flat [CNBC2]. | |||||
| - Interpretation: private money still pays up for AI chips (FuriosaAI at ~$2.9B post) while listed neoclouds fall, a public/private divergence in the same compute theme [FUR][CNBC3]. | |||||
| - Not researched this week [unavailable]: credit spreads and financing-cost data. | |||||
| This section is context only. It contains no buy or sell views, price targets, sizing or market-permission calls, and no OSINT. | |||||
| ### Rejected or set-aside evidence | |||||
| - Hyperscaler capex totals as 'capital flows': Company capex is reported spending, not a financing transaction. It is kept in N2 and left out of the ledger. CNBC3 | |||||
| - 'Upwind $400M' as cyber narrative evidence: Aggregator-only this run; no primary release fetched. Kept in the ledger as [VERIFY], not used for scoring. TS3 | |||||
| ### Sources | |||||
| - [AMZN] Amazon IR, Amazon.com Announces Third Quarter Results (2026-10-29). https://ir.aboutamazon.com/news-release/news-release-details/2026/Amazon-com-Announces-Third-Quarter-Results/ | |||||
| - [AMZT] StockAnalysis (call transcript), Amazon Q3 2026 earnings call transcript (2026-10-29). https://stockanalysis.com/stocks/amzn/transcripts/720308-q3-2026/ | |||||
| - [ANT] Anthropic, Anthropic files S-1 with the SEC for proposed initial public offering (2026-10-26). https://www.anthropic.com/news/s1-sec | |||||
| - [AP1] AP News, Anthropic files for an IPO that could top SpaceX's record debut (2026-10-26). https://apnews.com/article/anthropic-ipo-shares-public-ca2f4c282bef3201a392e59e3df2300c | |||||
| - [AP2] AP News, Malaysia seizes servers with advanced AI chips (2026-10-28). https://apnews.com/article/malaysia-us-ai-chips-export-transit-technology-79a912de57b21a4e59b27c9a86340202 | |||||
| - [BED] Bedrock Robotics (GlobeNewswire), Bedrock Robotics Raises $600 Million Series C to Scale Autonomous Construction Equipment (2026-10-26). https://www.globenewswire.com/news-release/2026/10/26/3388197/0/en/bedrock-robotics-raises-600-million-series-c-to-scale-autonomous-construction-equipment-across-u-s-sites.html | |||||
| - [BEDTC] TechCrunch, This startup's self-driving excavators help dig up $600M in new funding (2026-10-26). https://techcrunch.com/2026/10/26/this-startups-self-driving-excavators-help-dig-up-600m-in-new-funding/ | |||||
| - [CAN] Prime Minister of Canada, Canada announces landmark investment in Cohere to scale secure, sovereign AI (2026-10-29). https://www.pm.gc.ca/en/news/news-releases/2026/10/29/canada-announces-landmark-investment-cohere-scale-secure-sovereign-ai | |||||
| - [CNBC1] CNBC, Alphabet sinks as it holds 2026 capex unchanged (2026-10-28). https://www.cnbc.com/2026/10/28/alphabet-googl-earnings-q3-2026.html | |||||
| - [CNBC2] CNBC, Alphabet tanks nearly 13% for worst day ever, losing $500 billion in value (2026-10-29). https://www.cnbc.com/2026/10/29/alphabet-google-microsoft-msft-shares-today-earnings.html | |||||
| - [CNBC3] CNBC, AI buildout hits snag as Google and Microsoft put off raising capex forecasts (2026-10-29). https://www.cnbc.com/2026/10/29/microsoft-google-ai-capex-estimates.html | |||||
| - [FED1] Federal Reserve, Federal Reserve issues FOMC statement (2026-10-28). https://www.federalreserve.gov/newsevents/pressreleases/monetary20261028a.htm | |||||
| - [FRD] Dealroom News, UK chipmaker Fractile raises £577.4m Series C to challenge Nvidia (2026-10-29). https://dealroom.co/news/168114-uk-chipmaker-fractile-raises-577-4m-series-c-to-challenge-nvidia/ | |||||
| - [FRS] Sifted, Exclusive: Fractile raises £540m in new Series C funding, filings show (2026-10-29). https://sifted.eu/articles/exclusive-fractile-series-c | |||||
| - [FUR] FuriosaAI, FuriosaAI closes $620 million Series D to scale efficient, production-ready AI inference (2026-10-28). https://furiosa.ai/blog/furiosaai-620-million-series-d | |||||
| - [FURBW] Business Wire (via NatLawReview), FuriosaAI Secures $620 Million Series D (2026-10-28). https://natlawreview.com/press-releases/furiosaai-secures-620-million-series-d-meet-surging-enterprise-ai-inference | |||||
| - [GC] TechCrunch, General Compute raises $100 million Series A, countering the neocloud disaster narrative (2026-10-27). https://techcrunch.com/2026/10/27/general-compute-raises-100-million-series-a-countering-the-neocloud-disaster-narrative/ | |||||
| - [INF] PR Newswire, Infisical Raises $40 Million at $600 Million Valuation (2026-10-27). https://www.prnewswire.com/news-releases/infisical-raises-40-million-at-600-million-valuation-to-secure-the-ai-agent-economy-302920994.html | |||||
| - [KR] IBTimes KR, US Effectively Rejects South Korea's Bid for Export Control Exemption Program (2026-10-27). https://kr.ibtimes.com/us-rejects-south-korea-export-control-exemption-105054 | |||||
| - [META] Meta IR, Meta Reports Third Quarter 2026 Results (2026-10 (prior week, background)). https://investor.atmeta.com/investor-news/press-release-details/2026/Meta-Reports-Third-Quarter-2026-Results/default.aspx | |||||
| - [OAISN] OpenAI, OpenAI and ServiceNow expand partnership across enterprise workflows (2026-10-28). https://openai.com/index/openai-servicenow-partnership-expansion | |||||
| - [ORCL] Oracle, Oracle Brings Google TPUs to Oracle Cloud Infrastructure (2026-10-27). https://www.oracle.com/news/announcement/ai-world-oracle-brings-google-tpus-to-oracle-cloud-infrastructure-2026-10-27/ | |||||
| - [RT] Raise Track, Raise Track Update 2026-10-27 (2026-10-27). https://buttondown.com/raisetrack/archive/raise-track-update-2026-10-27/ | |||||
| - [S1] SEC EDGAR, Anthropic, PBC Form S-1 (2026-10-26). https://www.sec.gov/Archives/edgar/data/2130357/000162828026067168/anthropicpbc-sx1.htm | |||||
| - [TC1] TechCrunch, Anthropic officially files for its public debut (2026-10-26). https://techcrunch.com/2026/10/26/anthropic-officially-files-for-its-public-debut/ | |||||
| - [TR] TechRepublic, New US China Investment Proposal Could Reshape AI, Biotech and Chip Funding (2026-10-27). https://www.techrepublic.com/article/news-us-treasury-china-investment-rules-ai-biotech-chips/ | |||||
| - [TS1] Tech Startups, Startup Funding News Today, October 27, 2026 (2026-10-27). https://techstartups.com/2026/10/27/startup-funding-news-today-october-27-2026-bedrock-robotics-cent-epoch-nevis-north-vector-hyperbolic-more/ | |||||
| - [TS3] Tech Startups, Startup Funding News Today, October 29, 2026 (2026-10-29). https://techstartups.com/2026/10/29/startup-funding-news-today-october-29-2026-braid-casap-furiosaai-upwind-foundry-robotics-plato-more/ | |||||
| - [TT2] TechTarget, OpenAI's reported Google TPU deal tests AI chip economics (2026-10-28). https://www.techtarget.com/news/openais-reported-google-tpu-deal-tests-ai-chip-economics/873139/ | |||||
| - [YF2] Yahoo Finance, Anthropic's IPO filing left these key questions unanswered (2026-10-29). https://finance.yahoo.com/markets/article/anthropics-ipo-filing-left-these-key-questions-unanswered-090000298.html |
Quality gate: PASS WITH FLAGS (12/12 checks run, 0 failed). Flags: Single-source or secondary items: Korea export-exemption decision [VERIFY]; Fractile amount (filings only, £540m vs £577.4m); General Compute customer unnamed. Aggregator-only rounds (Upwind, Foundry Robotics, Machenta, Hyperbolic) are kept separate in the ledger and not used for scoring. The AP Malaysia article (28 Oct) was fetched in Thursday's test run; today's re-fetch timed out. Amazon's $578B backlog and 2027 capex remark come from a third-party call transcript, not the press release. Factor ratings are analyst judgement, not measured data. Credit spreads and financing-cost data not researched [unavailable]. No Canva design made.
Part 2 · AI ecosystem signals
Compute leaves home
Weekly Narrative Radar · AI ecosystem signals · W44 · 23–30 Oct 2026
Thesis. This week compute moved outside its home stacks. Google's TPUs are heading to a rival cloud, AWS growth reaccelerated on AI demand, and a government bought into a national model champion. Enforcement moved the other way and reached servers in transit.
1. AWS reaccelerates to 39%, with a $578B backlog
What happened. On 29 October Amazon reported AWS sales up 39% year on year to $46.0B, with AWS operating income of $17.8B [1]. On the call, management cited a $578B AWS backlog, about $220B of 2026 cash capex and "meaningfully more" in 2027 [2].
Why it matters. Interpretation: Cloud growth is the main evidence that the capex is being used. It is also why the market treated Amazon's negative free cash flow differently from Alphabet's (see Narrative N2).
Watch next. Q4 free cash flow as 2027 capex rises.
2. Google TPUs go to Oracle's cloud
What happened. On 27 October Oracle and Google said Google TPUs will be offered on Oracle Cloud Infrastructure from 2027, the first hyperscale cloud outside Google to do so [3]. Separately, The Information reported OpenAI may buy TPUs; neither company has confirmed it [4]. Microsoft said third-party GPU delays push some capacity into H1 2027 [7].
Why it matters. Interpretation: TPUs becoming a product other clouds sell makes Nvidia's main alternative a market, not a Google-only tool. This continues W43's TorchTPU signal.
Watch next. OCI pricing and capacity; any confirmation of the OpenAI purchase.
3. OpenAI moves deeper into ServiceNow workflows
What happened. On 28 October OpenAI and ServiceNow expanded their partnership: ServiceNow actions inside ChatGPT, OpenAI models in ServiceNow's development and security products, and ChatGPT Work and Codex for all ServiceNow employees [5]. The security product enters early access in January 2027, with general availability planned for Q2 2027 [5].
Why it matters. Interpretation: Labs are selling through the systems where enterprise work is already recorded, the same distribution logic as W43's Google Cloud deal.
Watch next. Early-access dates and any seat or usage numbers.
4. Canada takes an equity stake in Cohere
What happened. On 29 October Canada committed to an equity investment of up to about C$1.6B in Cohere, in stages, alongside NVIDIA, Bell and Schwarz Group [6]. Cohere committed to at least 1,000 Canadian technical jobs and at least C$1.7B of additional Canadian compute by 2030 [6].
Why it matters. Interpretation: Governments are moving from grants to equity, with location and hiring conditions attached (see Narrative N5).
Watch next. Total round size, the private investors' amounts and the first tranche.
5. Chip controls reach servers in transit and outbound capital
What happened. Malaysian customs seized servers with advanced AI chips suspected of export-control violations [8]. Treasury's proposed outbound-investment rules would cover AI, chips, quantum and biotech, with comments before final rules [9].
Why it matters. Interpretation: Enforcement is moving from what is shipped to where it transits and who funds it.
Watch next. The Treasury comment period and the outcome of the Malaysian case.
The pattern
Interpretation: Compute is leaving the stacks it was built in: Google silicon in Oracle's cloud, OpenAI agents inside ServiceNow, a government inside a model company's cap table. Forecast (low confidence): expect at least one more non-Google cloud to announce TPU capacity within six months.
Radar
| Signal | Layer | Direction | Confidence |
|---|---|---|---|
| AWS +39%, $578B backlog | Enterprise adoption | ↑ demand | High |
| Google TPUs on OCI | Compute/infra | ↑ access | High |
| OpenAI × ServiceNow | Apps/distribution | ↑ reach | High |
| Canada × Cohere equity | Capital/talent | ↑ state capital | High |
| Transit seizure, outbound rules | Geopolitics/supply chain | ↓ tightening | Medium |
Market context, not investment advice. Facts carry sources; interpretation and forecasts are labelled. Corrections are timestamped below.
Corrections: none.
Signal sources
- Amazon IR: Amazon.com Announces Third Quarter Results (2026-10-29)
- StockAnalysis (call transcript): Amazon Q3 2026 earnings call transcript (2026-10-29)
- Oracle: Oracle Brings Google TPUs to Oracle Cloud Infrastructure (2026-10-27)
- TechTarget: OpenAI's reported Google TPU deal tests AI chip economics (2026-10-28)
- OpenAI: OpenAI and ServiceNow expand partnership across enterprise workflows (2026-10-28)
- Prime Minister of Canada: Canada announces landmark investment in Cohere to scale secure, sovereign AI (2026-10-29)
- CNBC: AI buildout hits snag as Google and Microsoft put off raising capex forecasts (2026-10-29)
- AP News: Malaysia seizes servers with advanced AI chips (2026-10-28)
- TechRepublic: New US China Investment Proposal Could Reshape AI, Biotech and Chip Funding (2026-10-27)
Signals claim-to-source ledger (JSON)
The Friday email
The ranked narratives, the capital-flow ledger and the AI signals, once a week.
We only use your email to send this newsletter. Unsubscribe anytime.